Quick answer: estimate an IPTV reseller break-even point by separating fixed monthly costs from per-customer variable costs, calculating the contribution left after variable cost, then dividing fixed cost by that contribution. The result is a planning threshold, not a promise of profit. It is only useful when you enter current supplier terms, payment fees, customer-support time, refunds or adjustments, and realistic active-customer assumptions. This guide shows a transparent worksheet you can reuse without inventing prices or assuming a particular reseller plan.
TVMemberLink provides a reseller margin calculator and a reseller plan information page. Use the calculator to organize assumptions, then verify each input against written terms and your own records. This is general business education, not accounting, tax, investment, or legal advice.
What break-even means—and what it does not mean
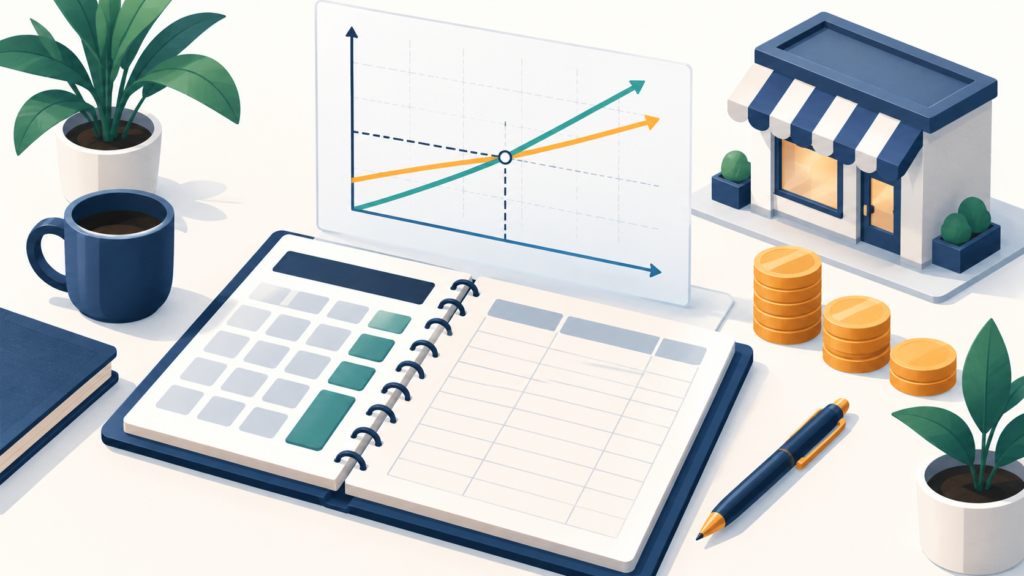
Break-even is the point where revenue equals the costs included in the calculation. At that point the model shows neither profit nor loss for the selected period and assumptions. The U.S. Small Business Administration describes the basic unit formula as fixed costs divided by selling price per unit minus variable cost per unit. For a reseller, the “unit” must be defined carefully: it could mean one active customer for one billing period, one account allocation, or another unit that matches the supplier’s actual billing structure. If your units do not match, the result will be misleading.
Break-even does not prove that demand exists, that a supplier’s service is suitable, or that a business is authorized to resell anything. It does not include every possible cost unless you deliberately include it. It also does not predict customer churn, delayed payments, support spikes, taxes, currency movement, or outages. Treat it as one scenario-planning tool among several. Ask an accountant or qualified local adviser about tax treatment and recordkeeping obligations relevant to your situation.
Define the model period and unit first
Choose a consistent period, such as one month. Do not mix monthly revenue with an annual supplier cost unless you convert the annual cost into a monthly equivalent and clearly note the timing of cash payments. Then define one unit. If a plan allocates credits that can be consumed at different rates, a “credit” may not equal one customer-month. Read the supplier’s current terms and map the exact unit to an actual transaction.
Write four definitions at the top of the worksheet:
- Period: the calendar month or another fixed window used for every input.
- Unit: the customer service period or allocation being sold.
- Revenue per unit: the amount you actually expect to retain for that unit, excluding taxes collected for others if applicable.
- Variable cost per unit: supplier consumption and direct costs that rise when you add one more unit.
Do not use an advertised retail price as if it were your collected revenue. Discounts, payment failures, processing fees, refunds, currency conversion, and unpaid invoices can change the amount retained. Keep the model simple at first, but make the assumptions explicit.
Step one: identify fixed costs
Fixed costs stay broadly similar within the selected range of activity. They may include an accounting or support tool subscription, a basic website expense, a fixed payment-platform fee, bookkeeping, or a minimum supplier commitment. A cost is not automatically fixed forever; it is fixed only for the period and scale you are modelling. If adding staff or a higher plan changes the expense, that cost becomes step-fixed and should be included in the scenario where the threshold is crossed.
Create a table with each cost, amount, billing period, currency, evidence, and confidence level. Use invoices or written quotes where possible. For a cost paid annually, divide it across the months for the profitability view while separately noting that cash may leave your account in one month. Profitability and cash flow are related but not identical.
Possible fixed-cost rows include:
- website hosting or domain costs used for the operation;
- customer-support or record-management software;
- fixed account or platform charges;
- professional services and bookkeeping;
- advertising commitments that do not vary with each sale;
- minimum monthly purchase or account fees, if the current agreement has them.
Do not list a cost simply because it sounds standard. Include only costs that apply to your actual model, and retain the source document. If an item varies with sales, allocate it to the variable-cost section or explain the chosen allocation.
Step two: calculate variable cost per unit
Variable costs rise with each additional sale or active customer. For a reseller model, this may include the supplier allocation consumed by that customer, transaction fees, commissions, and a realistic amount of support time if you value labor per case or per customer. Include refunds, replacements, or credit adjustments only based on actual terms or measured history; if no evidence exists, show them as a separate sensitivity allowance rather than pretending to know the rate.
Support time matters even if the owner does not draw a salary today. Record the minutes spent on initial setup, routine questions, renewal reminders, and escalations. Multiply expected hours by a reasonable internal hourly value. This does not mean every small business must pay that amount immediately; it makes the economic cost visible. A plan that only breaks even when support labor is valued at zero may be a demanding hobby rather than a sustainable business.
Payment costs can combine a percentage of the transaction with a fixed charge. If so, estimate them per unit using the actual payment mix and the current processor schedule. Do not copy a fee from an old blog article. Verify it directly with the provider, and consider international cards or currency conversion only if those transactions apply to your customers.
Step three: find contribution per unit
The contribution per unit is the amount remaining after variable costs are subtracted from revenue per unit. Use:
Contribution per unit = net revenue per unit − variable cost per unit
If contribution is zero or negative, selling more units does not solve the underlying model under those assumptions. Recheck your inputs, supplier consumption, discounts, and costs. Do not “fix” the spreadsheet by removing a real cost. If contribution is positive, divide fixed costs by contribution to estimate the break-even units:
Break-even units = fixed costs for the period ÷ contribution per unit
Round the result up to the next whole unit if customers or units cannot be fractional. For an illustrative example only, imagine a generic service operation has 600 units of fixed cost, retains 30 currency units per customer-period, and incurs 18 currency units in variable costs. Contribution is 12, so the calculation is 600 divided by 12, or 50 customer-periods to break even. These values are invented solely to demonstrate arithmetic; they are not TVMemberLink prices, supplier terms, or a forecast.
Step four: include owner time and customer acquisition
Customer acquisition is easy to undercount. Track the direct spend for an advertisement or campaign and estimate the time spent creating content, answering presales questions, and following up. If acquisition spending is variable by customer, include it in the variable cost. If it is a fixed monthly campaign budget, include it as fixed cost. Choose one treatment and avoid counting the same expense twice.
Owner time can be recorded as a separate line even when no payroll payment occurs. This allows two views: cash break-even and economic break-even. Cash break-even asks whether money coming in covers cash going out during the period. Economic break-even also assigns a value to labor and other resources contributed by the owner. Both views are useful, but they answer different questions.
The SBA’s general break-even guidance emphasizes identifying fixed costs, selling price, and variable cost. A small reseller should extend that basic model carefully, not replace it with a complicated forecast before basic records exist. The SBA’s business-management resources also discuss bookkeeping and cash-flow projections; use current professional advice for local accounting treatment.
Build low, base, and high scenarios
A single number can create false confidence. Build three scenarios with the same definitions and period:
- Low: fewer active customers, higher support minutes, some failed payments, and conservative retention.
- Base: use measured enquiry and conversion evidence, not a target selected to make the plan appear viable.
- High: show plausible upside only, and do not treat it as guaranteed revenue.
Change one assumption at a time first. For example, keep costs fixed and test how the result changes when customer count falls. Then restore customer count and test support time. This makes the driver of risk visible. After that, combine several adverse assumptions in the low case to see whether the model remains tolerable.
Record the source and date for each input. Supplier pricing can change; payment fees can change; customer behavior can differ from the first month. Add a review date to the worksheet. A calculation without input dates becomes stale and may be repeated long after its assumptions have stopped being valid.
Cash timing and working capital
A profitable model can still run short of cash if supplier payments are due before customer receipts arrive. Create a cash calendar that marks the date each supplier charge, software bill, customer payment, refund window, and tax-related reserve is expected. Compare weekly or monthly balances, not only total revenue and cost. If you must prepay an allocation, identify how much cash is tied up and what happens if demand is lower than expected.
Do not treat uncollected invoices as cash. Separate sales booked from payments received, and distinguish refundable deposits from earned revenue according to the advice applicable to your accounting method. The SBA notes that bookkeeping and cash-flow projections help business owners track capital and anticipate needs. A qualified accountant can advise whether cash or accrual accounting and any specific records apply to your circumstances.
Common modeling errors
Mixing the plan’s units
If the supplier charges by credit, month, screen, or account, do not assume those units are interchangeable. Confirm how a unit is consumed and match the model to that rule.
Ignoring failed payments
Model the collected amount, not just invoices issued. Track successful, pending, reversed, and refunded transactions separately.
Using average support time from memory
For a few weeks, record actual minutes by case type. A rough log is better than an invented “zero support” assumption.
Counting the same cost twice
Decide whether campaign spend is fixed or per acquisition. Allocate it once, document the approach, and keep the same method across scenarios.
Confusing margin with markup
Margin is usually measured relative to revenue; markup is measured relative to cost. Label the formula and denominator. Do not compare percentages without checking which one is being used.
Assuming growth fixes weak contribution
More sales can magnify a negative contribution and raise support load. First make sure each additional unit contributes positively after variable costs.
Use a worksheet in a repeatable way
- Set the period, unit, currency, and model date.
- Enter confirmed fixed costs with evidence and billing cadence.
- Enter current variable supplier cost and payment cost per unit.
- Estimate support minutes, acquisition, and adjustments separately.
- Calculate net revenue, variable cost, contribution, and break-even units.
- Compare the result with observed customer count and cash timing.
- Run low, base, and high scenarios and note what changed.
- Review after the next billing cycle and replace assumptions with actuals.
Keep the underlying rows visible. A calculator output is not auditable if no one can see which numbers generated it. Add a notes column for the source, date, whether the value is estimated or observed, and who verified it. If another team member changes an input, record why.
The FTC recommends that businesses know what sensitive personal information they hold, protect it, and dispose of it securely. A financial worksheet should generally use aggregate amounts and transaction references rather than storing customers’ passwords, full payment card details, or playlist URLs. Keep access limited and use a separate secure system for any information genuinely needed to deliver service.
Frequently asked questions
What is the basic break-even formula?
Fixed costs divided by contribution per unit, where contribution equals net revenue per unit minus variable cost per unit. Ensure the unit and period match.
Should I include my own support time?
Yes, at least in an economic view. You can maintain a separate cash-only view, but a zero value for owner time can hide the workload required.
Are the example amounts real?
No. They are fictional values used only to demonstrate arithmetic and do not represent any service price, supplier rate, or forecast.
Can a calculator determine whether a reseller opportunity is authorized?
No. A calculator only processes inputs. It cannot establish supplier rights, local rules, product suitability, or a commercial agreement.
How often should the model be updated?
Review it whenever supplier terms, payment costs, support workflow, or customer behavior changes, and at least after each early billing cycle while the model is being validated.
What if contribution is negative?
Do not increase volume on that assumption. Verify the costs, pricing, and unit definition, then revise the model or decide not to proceed.
Conclusion: treat break-even as a living test
A credible reseller break-even worksheet is built from written terms, actual operating costs, measured support effort, and a clearly defined unit. Calculate contribution before dividing fixed costs, separate cash timing from profitability, and stress-test the assumptions. Do not use an optimistic customer target to disguise weak unit economics.
To organize an initial estimate, use the reseller margin calculator, then compare its inputs with the current reseller plan details. If you are new to the business workflow, the reseller onboarding guide can help identify operational questions. For a service enquiry, use the site’s contact page or official Telegram support group. Never send credentials or complete payment details in a public message.
References: U.S. Small Business Administration: break-even formula; SBA: bookkeeping and cash-flow management; FTC: protecting personal information in a business.
